August 2026 Net Worth Update: Back Above My Old Peak at $2.33M

Last month I paid off the car loan. This month, nothing happened — and net worth quietly hit a new high of $2.33M, up $66.7K, finally clearing the peak I set in May before I bought the car. No bonus, no stock vest — just steady paychecks and a market that cooperated.
Quick TL;DR
- Total Net Worth: $2.33M (up ~$66.7K from $2.259M)
- Key Driver: No bonus or vest this month — just steady paychecks, regular contributions, and a strong month in the market
- Spending: ~$3.9K core, excluding the mortgage — under my $5K target
- FI Progress: 46.5% toward $5M (up from 45.2%)
The Bottom Line
| Metric | Value | Change |
|---|---|---|
| Assets | $2.654M | +$66.0K |
| Liabilities | $328.31K | -$0.8K |
| Total Net Worth | $2.326M | +$66.7K |
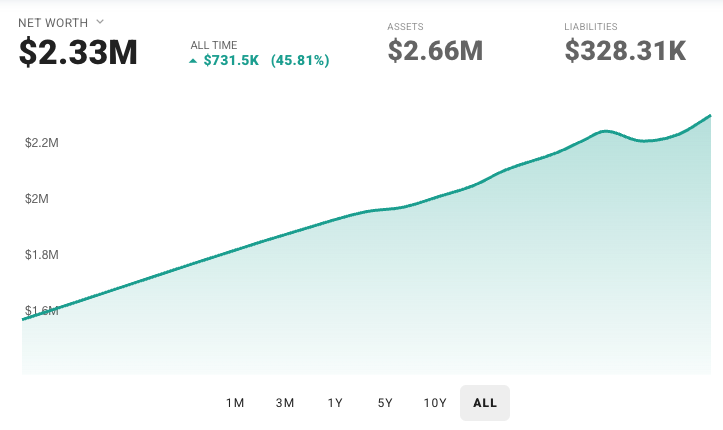
Net worth $2.33M. Up $731.5K (45.81%) all-time. You can see the June dip in the line — and that it's now above every point before it.
Assets rose $66K, liabilities barely moved. Nothing was sold, nothing was borrowed — the number just went up.
| Month | Net Worth | Growth | New Money In | Market Did | Investable |
|---|---|---|---|---|---|
| Jan 2026 | $2.080M | +$38.6K | $24.0K | $14.6K | $1.764M |
| Feb 2026 | $2.134M | +$53.8K | $18.2K | $35.6K | $1.809M |
| Mar 2026 | $2.197M | +$54.0K | $27K | $27K | $1.872M |
| Apr 2026 | $2.240M | +$43K | $9K | $34K | $1.915M |
| May 2026 | $2.270M | +$30K | $4.5K | $25.5K | $1.931M |
| June 2026 | $2.235M | -$34.6K | -$14.2K | -$20.4K | $1.881M |
| July 2026 | $2.259M | +$23.9K | +$11.1K | +$12.8K | $1.805M |
| Aug 2026 | $2.326M | +$66.7K | +$10.8K | +$55.9K | $1.871M |
| 2026 YTD | — | +$275.4K | +$90.4K | +$185.0K | — |
Growth = New Money In + Market Did. August's New Money In is just regular paycheck savings and contributions — no bonus, no vest to pad it. The rest came from the market.
Best month on the table, and none of it was a windfall — $10.8K from showing up and saving like usual, $55.9K from the market doing its job. More importantly: $2.326M clears May's old peak of $2.270M by about $56K. Whatever the car cost me, it's behind me.
Assets Breakdown: $2.654M
| Asset Class | Value |
|---|---|
| Taxable Investments | $1.03M |
| Tax-Deferred Investments | $389.8K |
| Tax-Free Investments | $350.4K |
| Cash & Equivalents | $84.5K |
| Crypto | $16.2K |
| Investable Portfolio | $1.87M |
| Real Estate, Business & Vehicle | $783.1K gross / $454.8K equity |
| Total Assets | $2.654M |
Liabilities: $328.31K
- Mortgage: $328.31K — down another ~$800, autopilot as always.
- Auto Loan: $0 — still gone, since July.
- Credit Cards: $0 — paid in full.
One line. Same as it's been since the loan payoff. Boring, on purpose.
Paychecks and Contributions
Two regular paychecks in August, each about $9.75K gross — no bonus, no RSU vest this time. Take-home was small on purpose: 401k, Mega Backdoor Roth, ESPP, and HSA all took their cut before the money hit checking, leaving under $4.6K combined.
YTD Front-Loading (through August)
| Account | YTD | % of 2026 Limit |
|---|---|---|
| 401k Pre-Tax | $18.4K | 75% |
| Mega Backdoor Roth | $28.4K | 61% |
| HSA (Emp + Employer) | $6.1K | 70% |
| ESPP | $9.6K | toward Dec purchase |
Every account is still on pace, some ahead of it. ESPP is just quietly stacking up cash for the December purchase.
Side-Quest: Churning Bank Bonuses
Separately, I started chasing a couple of bank account bonuses this month — small potatoes next to the numbers above, but worth a mention:
- Chase: $900 for parking $15K in savings for 90 days, plus one direct deposit. Funded August 11 — the direct deposit is queued, payout lands in November.
- Citi: $475 for moving $5K over and setting up a couple of direct deposits. Opened August 13.
That's $1,375 for tying up $20K for about three months — roughly 28% annualized on cash that was otherwise earning next to nothing. None of it has paid out yet, so it's not in any of the numbers above. Just money quietly cooking in the background.
Spending: $6.1K
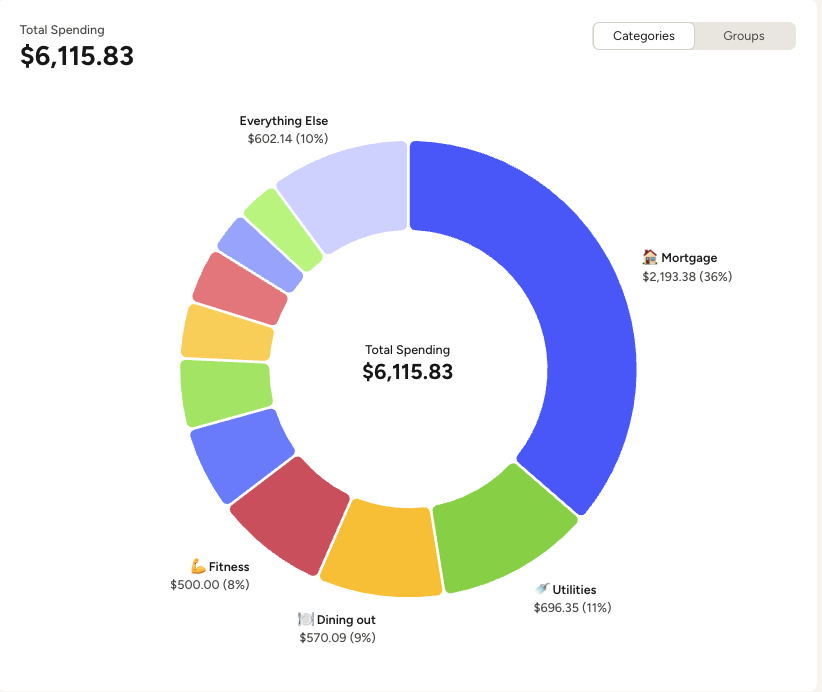
August spending: $6,115.83. No outlier slice this month — just the usual categories.
Total August spending was $6,115.83. Take out the mortgage ($2,193.38) and core spend was ~$3,922 — comfortably under my $5K target. The rest was ordinary: utilities ($696), dining out ($570), fitness ($500), and a handful of smaller categories. Nothing to explain away this month, which is its own kind of nice.
What the Car Round-Trip Actually Cost
The timeline: $2.270M in May (the peak) → $2.235M in June (bought the car, $138K all-in) → $2.259M in July (paid off the $99K loan) → $2.326M now, about $56K above where I started.
The real cost was never $138K — the car's still an asset. It's the gap between what I paid and what it's worth today: about $26K, mostly taxes and fees. I made that back in about two months of regular saving and market growth. Net worth's higher now than the day before I bought it, and I still drive it every day. Worth it.
Reflections
- Rules beat decisions. I didn't make a single active move this month — just automatic contributions and a market doing its thing. That's the whole recipe, and it's the one I can count on repeating.
- Setbacks fill in faster than they feel like they will. The car's real cost was about $26K I'll never get back. Two months later, I'm $56K past where I was before I bought it.
- Idle cash should have a job. $20K sitting in savings just picked up $1,375 in bank bonuses — same instinct as financing the car instead of selling investments to pay for it.
Next up: nothing planned. Just watching the ESPP balance build and those bank bonuses land.
Your turn. Has a purchase or a bad month ever felt way bigger in the moment than it turned out to be once you looked back? Drop a comment — I'd like to hear how long it actually took you to stop thinking about it.
Join the Quest