January 2026 Net Worth Update: I Spent More Than I Made (On Purpose)

This month, I technically spent more than I made.
My checking account saw $3,802 in deposits. My spending was $6,007.
In a normal world, that's a problem. In my world, that's the plan.
January was the start of my aggressive front-loading strategy for 2026. I diverted nearly every available dollar into tax-advantaged accounts—401k, Mega Backdoor Roth, HSA—before it even hit my bank account. The result? A cash flow crunch on paper, but a $24K injection into my net worth.
Here's the breakdown of a month where I felt "broke" but actually got richer.
Quick TL;DR
- Total Net Worth: $2.08M (up $38.6K from last month)
- Key Driver: Front-loading retirement accounts + RSU vesting = $24K invested in one month
- Spending: $6,007 (over my $5K target, but for a good reason)
- FI Progress: 41.6% toward my $5M goal
The Bottom Line
| Metric | Value | Change |
|---|---|---|
| Assets | $2.43M | +$32.8K |
| Liabilities | ($349.6K) | -$5.8K |
| Total Net Worth | $2.08M | +$38.6K |
I'm firmly in the $2M club now. Growth this month was a mix of raw savings ($24K in new contributions) and the market doing its thing ($14.6K in growth).
Assets Breakdown: $2.43M
| Asset Class | Value |
|---|---|
| Taxable Brokerage | $886.3K |
| Real Estate & Business | $671.1K |
| Retirement Accounts | $615.7K |
| Cash & Equivalents | $245.9K |
| Crypto | $16.2K |
Retirement accounts are up from $577K in November. That's the front-loading already paying off.
Liabilities: ($349.6K)
Nothing exciting here. Autopilot.
- Mortgage: ($333.5K) — Slowly ticking down.
- M1 Loan: (~$16K) — Almost done with this one.
- Credit Cards: $0 — Paid in full, as always.
Income & Spending: Artificial Scarcity in Action
This is the part I'm most proud of. My gross income was $52,438 (inflated by RSU vesting), but my actual take-home was only $3,802.
Where did the rest go?
| Deduction | Amount |
|---|---|
| 401k (Pre-Tax) | $1,943 |
| Mega Backdoor Roth | $4,627 |
| HSA | $783 |
| ESPP | $6,941 |
| Total from Paycheck | $14,296 |
Add the vested RSUs (net ~$9.7K), and I put over $24K into assets in 31 days.
Spending: $6,007
Higher than my $5K target, and one category is to blame: groceries at $1,313.
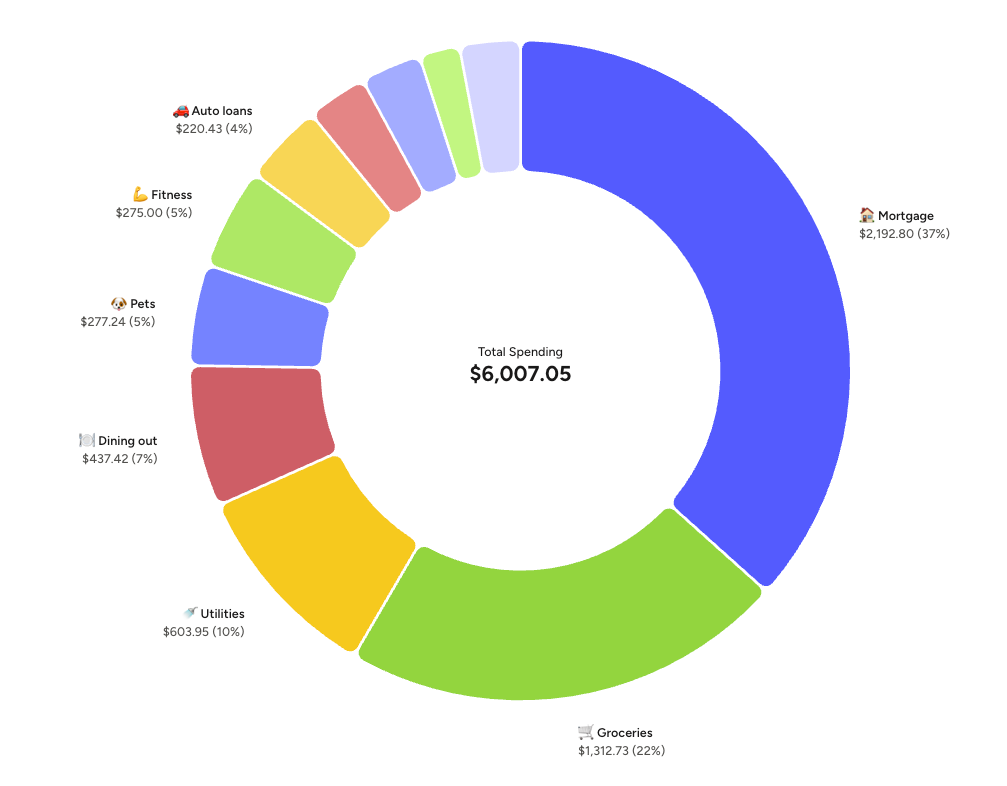
January 2026 spending breakdown. Groceries dominated at 22%, but dining out dropped to $437.
This wasn't mindless spending though. I made a conscious shift to healthy eating and meal prepping this month. That $1,313 includes a one-time buy of glass containers and kitchen gear to support the new habit. I'm swapping dining out dollars (down to $437) for grocery dollars. I'll take that trade every time.
How I Survived the Cash Crunch
My spending ($6K) exceeded my take-home ($3.8K) by $2.2K. So where did the money come from?
My YNAB buffer. I'm currently living on money I earned 3 months ago. This buffer is what lets me front-load aggressively without panicking when the checking account looks low. It worked exactly how I planned it when I built the buffer last fall.
Reflections
- Front-loading works. Seeing small paychecks stings, but knowing I've already filled a huge chunk of my 2026 retirement buckets by January? That feels good.
- Health over convenience. The grocery bill was high, but I'd rather spend $1K at the grocery store than $1K on takeout. That's a trade I'll make every time.
- Momentum is real. At $2.08M, the day-to-day volatility doesn't rattle me like it did at $1M. There's a steadiness now that makes it easier to stay the course.
Next month: keep going. The goal is to finish maxing the 401k and Mega Backdoor Roth by end of Q1.
Join the Quest